Commission Accrual Timing and Retroactive Tier Adjustments in Financial Close
Retroactive tier adjustments force finance to revise commission accruals deal by deal at close.
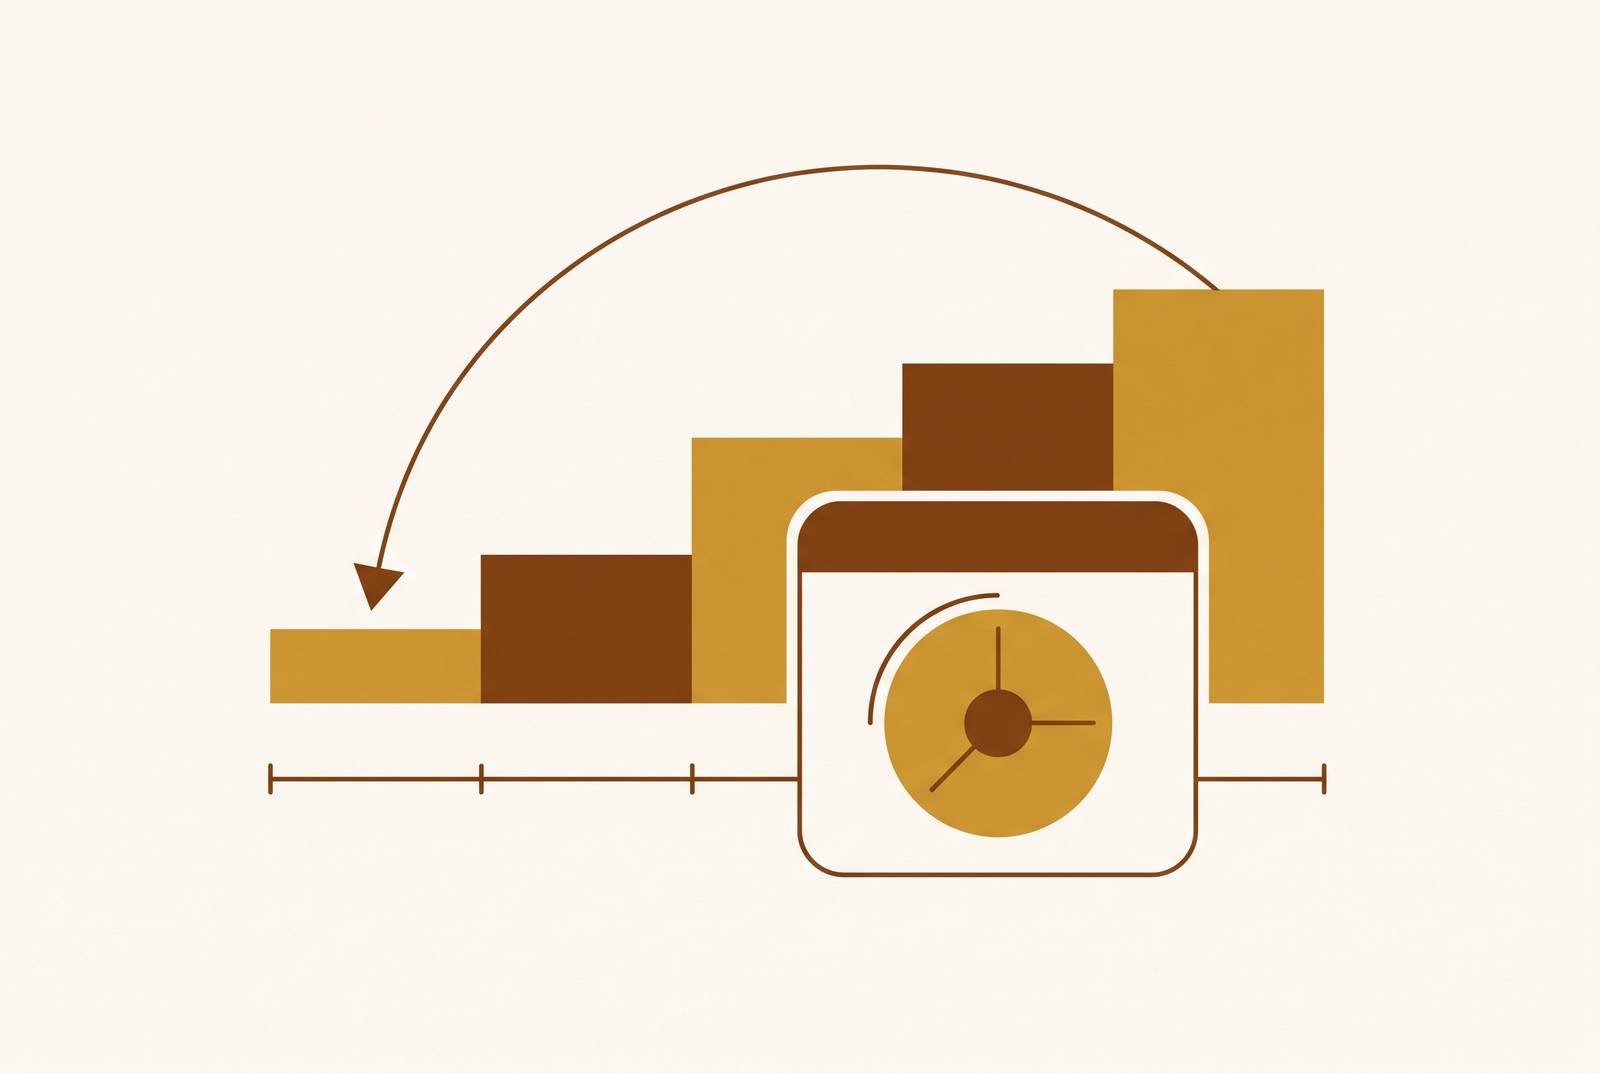
Commission expense must be accrued in the period revenue is recognized. That requirement forces finance teams to carry an estimated liability on the books for tiered sales compensation plans before anyone, including the rep, knows what the final payout will be. Flat and prospective-tier plans make this estimate imprecise but workable. Retroactive tier plans make it structurally unstable, because the rate that applies to every deal closed in the period cannot be fixed until the period itself is finished.
Why commission accrual for tiered plans cannot wait
Accrual accounting does not give finance the option of waiting for certainty. Revenue recognized in a period must be matched with the expenses associated with generating it, and commission expense is one of those expenses, so an estimated liability has to go on the books in the same period the related revenue lands, regardless of whether payroll has run the final commission calculation yet. This is a compliance obligation that finance teams must meet regardless of how confident they feel about a quarter's numbers.
For a flat-rate plan, or a tiered plan where rates apply only prospectively to future deals, that obligation is manageable. Each deal's commission is calculable from data already sitting in the CRM: a known deal value, a known rate, a known rep. Future deals do not reach backward and change what a prior deal was worth in commission terms, so the accrual built mid-period holds up reasonably well against the final number. Retroactive tier plans break that assumption. A rep's total attainment for the period is unknown until the period closes, and because the applicable rate for every deal in the period depends on that final attainment number, the accrual itself is a moving target from day one. Finance ends up posting a liability based on an assumed tier, revising that assumption as attainment data accumulates, and then truing it up at close, a multi-step estimation process in which each revision can require pulling individual deal records back out for re-examination.
Retroactive vs. prospective tiers: accrual impact
The mechanical distinction between retroactive and cumulative tier structures determines how much damage a single late-period deal can do to an accrual. In a cumulative or prospective model, a higher commission rate applies only to the dollars sold above a given threshold. A rep who crosses into a new tier late in the quarter sees that new rate apply to the incremental deals that pushed them there and to anything booked after, but the deals booked earlier in the period, at the lower tier, stay priced the way they were when they closed. Finance can accrue incrementally under this model: each deal carries a rate known at the time of booking, and only the marginal deals above a boundary change.
A retroactive tier structure works differently. The moment a rep crosses the threshold, every deal from earlier in the period gets repriced at the new rate. Picture a deal booked early in the quarter and accrued at a Tier 1 rate. A later deal in the same quarter pushes the rep's cumulative attainment past the threshold for Tier 2. Under a retroactive structure, that earlier deal is recalculated at the Tier 2 rate, along with every other deal the rep closed that period, producing what functions as a restatement of the period's commission expense rather than a simple addition to it. That restatement is not only a payroll matter; it is a change to a balance sheet liability, and it has to be traceable and defensible to auditors. The volatility concentrates near tier boundaries: for a rep whose attainment tracks close to a threshold for most of the period, finance may need to carry two separate liability estimates in parallel, one built on the assumption the rep crosses, one on the assumption they don't, until the data resolves which one was right.
How collapsing deal data destroys the audit trail
Spreadsheet-based and CRM-export-based commission processes share a common failure mode: they aggregate. A rep's total payout for the period gets reduced to a single number before it ever reaches payroll, with no record preserved of which deal contributed what amount at what rate. That aggregation is fine when nothing changes after the fact. It becomes a serious liability the moment a retroactive tier adjustment hits, because the revised payout figure lands in payroll with no way to trace which prior deals were repriced, by how much, or why.
Sales operations teams have lost weeks to exactly this kind of reconstruction, chasing down a discrepancy in a commission total only to discover that deal splits, overlay rules, and the correct accelerator tier had never been accounted for correctly. That is the reconstruction cost of losing deal-level attribution: not a minor reconciliation task, but a multi-week forensic exercise to rebuild data that should have existed all along. Accrual reconciliation depends on matching the estimated liability to the actual payout at the deal level, confirming that the rate applied to each deal corresponds to the tier the rep had actually achieved at the time payment was calculated, and that the movement from estimate to final figure can be explained deal by deal. A single aggregate payout number cannot support that kind of reconciliation. It can tell an auditor that a number changed. It cannot tell them why, or whether the change was calculated correctly.
The accrual estimate process under retroactive tiers
A defensible mid-period accrual under a retroactive tier plan requires finance to track each rep's attainment at the deal level throughout the period, beyond maintaining a running payout estimate. The applicable rate for every deal booked so far depends on where the rep's total attainment lands at period-end, so the accrual has to be built on attainment data, not on a snapshot of payouts calculated under an assumption that may not hold.
In practice, that means finance needs a live view into CRM pipeline, one that separates closed-won deals from deals still in progress, applies probability weighting to the projected ones, and updates the tier assumption as new deals close out. That is work a monthly payroll export cannot support, because by the time payroll data exists, it has already collapsed into the aggregate figures described above. Mid-period complications multiply the difficulty: territory changes, contract amendments, deal splits, and refunds that land after a cutoff date each introduce new uncertainty into where a rep's attainment actually sits relative to a tier boundary, and each can force a revision of the entire period's accrual rather than just the commission on one deal. Adding to the difficulty, commission payout timing and revenue recognition timing frequently diverge: commissions often get paid at booking, while revenue is recognized over the life of a contract term. That divergence means finance has to track recognized-revenue attribution separately from the cash payout schedule. Defining a commissionable event clearly, and aligning it as closely as possible to the revenue recognition schedule, narrows that gap and makes the mid-period accrual easier to hold with confidence.
How the true-up compounds without deal-level data
The true-up at period close is where every upstream decision about data and process either pays off or collapses. Finance has to compare the liability accrued through the period against the actual commission expense, explain the variance between the two, and post an adjusting entry, and all of that depends on the ability to trace the final payout back to the specific deals and rates that produced it.
When a retroactive tier adjustment hits near period-end, the resulting true-up is typically larger than anything a prospective-tier plan would generate, because the adjustment reprices the whole period's deals rather than only the deals above a marginal line. A single late deal that pushes a rep into a higher tier can produce a true-up that dwarfs the commission value of that one deal. Without deal-level records behind the accrual, finance cannot confirm the repricing was done correctly. They can see that the payout changed. They cannot verify that every prior deal in the period was included in the recalculation, that the correct threshold and rate were applied, or that any clawbacks or offsetting adjustments were properly netted against the increase. That gap turns into an audit defense problem, because supporting schedules have to demonstrate that each piece of commission expense was calculated according to the plan document on file, and a single-line payroll entry cannot do that. When several reps cross tier boundaries in the same period, a pattern common in strong quarters, the compounding effect on the aggregate true-up can become material at the company level, and the inability to break that figure down by rep and by deal makes the variance both slow to explain and hard to trust once explained. None of this is a close-process failure that can be fixed at close. It is the downstream consequence of a data decision made earlier, when deal-level attainment data was allowed to collapse into aggregate payout figures instead of being preserved throughout the period.
Deal-level traceability requirements for data and process
Solving this at the source means preserving, for every commission payment, the underlying deal record, the attainment calculation in effect at the time of payment, the tier and rate applied, any adjustments layered on top such as clawbacks, splits, or overlays, and a log of when the calculation was approved and by whom. Preserving this is an input requirement, because finance can only build a defensible mid-period accrual if it can pull a current, deal-level view of each rep's attainment rather than a summary of what got paid out last month.
The data has to originate from the CRM rather than from a spreadsheet or a payroll export, because the deal record lives in the CRM, and commission calculations need to be driven from the same source feeding revenue recognition so the two sets of books can be reconciled against a shared record. That source has to be clean before any of this works. Missing close dates, untracked activity, and incorrect deal attribution corrupt the commission calculation before any downstream system has a chance to process it; moving to a more structured commission process without first auditing the CRM data underneath it only automates the existing errors rather than removing them. The integration between CRM and commission calculation has to operate at the deal level as well. Batch imports of aggregate rep totals cannot support deal-level attribution or mid-period accrual updates, because by the time the aggregate figure arrives, the information needed to trace it back to individual deals has already been stripped out.
Locked pay periods, logged approvals, and close integrity
Deal-level data solves the problem of attributing payouts to source deals, but it needs a control layer around it to stay intact once a period closes. A locked pay period means that once a commission period has been closed and approved, no retroactive change to deal data, plan rules, or rep attainment can alter the calculated payout without an explicit override, logged and attributed to a named approver. Without that lock, a retroactive tier adjustment applied after close, triggered perhaps by a deal booked in the period but recognized later, or by a contract amendment signed after the fact, can silently rewrite a payout that has already been accrued, paid, and reconciled. That produces a variance with no audit trail and no clear explanation.
Logged approvals support the audit defense directly. They establish that a payout figure was reviewed and approved by a specific person at a specific time, under a specific version of the plan document, and that any change made after that point was a deliberate decision rather than a silent recalculation. Locking and logging together let finance treat a closed commission period as a stable liability: the accrual gets finalized, the true-up gets posted, and the period closes with confidence that the number will not move again without a traceable decision behind it. Auditability, the ability to trace any payout back to its source deal data, the rules applied, and the approver who signed off, functions as a design requirement for the commission process itself, serving a purpose beyond reporting. It is the condition that makes every other step in the close process defensible. Deal-level data, structured calculation, locked periods, and logged approvals together are what separate a commission process that can actually support a financial close from one that simply produces a number and hopes it holds.